


- Pocheon City’s 2026 regular property tax rollout demonstrates that the legitimacy of local governance relies on operational clarity, digital convenience, and transparent resource allocation.
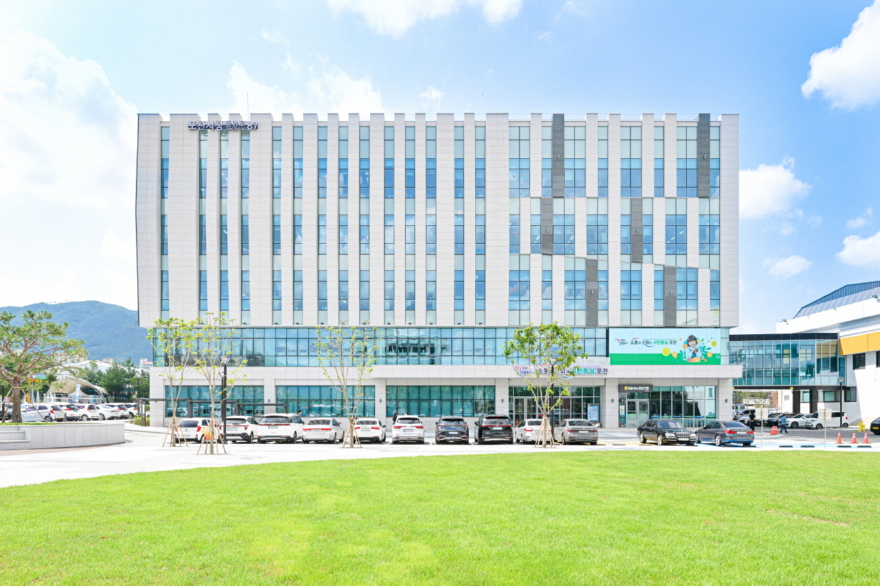
Local public finance is rarely sustained by grand rhetoric. Instead, it relies on the unvarnished fundamentals: taxes collected on time, assessment procedures that citizens deem fair, and a friction-free payment architecture. Pocheon City’s recent rollout of its July 2026 regular property tax assessments and its concerted push to maximize timely collections carry significance far beyond routine tax administration. While tax notifications are a repetitive annual ritual, it is precisely within this predictability that a municipality demonstrates its foundational administrative health.
The city has issued property tax bills targeting owners of residential homes, commercial structures, and vessels based on ownership status as of the June 1, 2026 statutory assessment date, combining regional resource facility and local education taxes into a unified bill. For residential properties, assessments below 100,000 won are billed in full this July, while amounts exceeding that threshold are split evenly between July and September installments. On the surface, this reads as a standard administrative update. Yet, this very familiarity is a crucial asset for local governance; public finance must secure public trust through arithmetic precision and predictability before it can ever chase grand structural policies.
While property taxes are an inevitable burden for citizens, they serve as the most practical fiscal lifeblood for a municipal government. Public infrastructure, social safety nets, and day-to-day administrative services are fundamentally dependent on a stable local revenue base. This reality carries added weight as Pocheon steers its current policy agenda toward establishing its new Population Growth Bureau, enhancing residential livability, repurposing the returned 6th Corps military site, and diversifying its agricultural and regional economic layout. Grand blueprints require robust fiscal scaffolding. No matter how visionary a local government's long-term strategy may be, it cannot survive on an unstable revenue foundation. Thus, the stable collection of regular property taxes is not merely an extraction of capital, but the minimal baseline that makes long-term governance possible.
Ultimately, the measure of effective tax administration lies not in the aggressiveness of its collection enforcement, but in minimizing the friction experienced by the taxpayer. Pocheon’s deployment of diverse non-face-to-face payment gateways—ranging from CD/ATM integration and postal service coordination to virtual accounts, automated response systems (ARS), specialized local revenue accounts, and digital notifications via commercial banking applications—must be understood within this framework. In the modern era, the competitiveness of tax administration is dictated by convenience as much as by legal rigor. While paying taxes is a mandatory civic obligation, a convoluted and hostile process rapidly erodes public trust. Conversely, when procedures are seamless and guidelines are transparent, taxpayers exhibit far greater compliance and acceptance.
For recurring tax categories like the property tax, the user experience itself becomes a direct critique of local governance. Minor details—whether physical bills arrive accurately, whether lost notifications can be instantly verified, the diversity of payment channels, and whether preventative measures are taken to avoid deadline congestion—carry significant administrative weight. Pocheon’s reactive counseling protocols through its civil call center and tax division, alongside expanded multi-channel public relations, are logical extensions of this user-centric governance. Citizens rarely evaluate a city based on sprawling geopolitical visions; they feel its competence in the quiet precision of daily interactions.
Trust materializes only when an administration treats taxation not as an exercise in raw extraction, but as an explainable, rules-based institution.
Naturally, convenience alone cannot validate a tax system. The architecture must be anchored in structural equity and transparency. Property taxation demands rigid institutional clarity regarding assessment dates, tax bases, and split-payment thresholds, ensuring that taxpayers clearly comprehend the rationale behind their bills. Civic compliance is rarely governed by the tax rate alone; it hinges on the perceived legibility and fairness of the system. In this context, Pocheon's commitment to swiftly resolve missing or lost bills carries symbolic weight. Administrative credibility is accumulated in the micro-management of individual grievances.
Yet, a critical distinction must be maintained: stabilizing public revenue does not automatically equate to a successful administrative outcome. The final audit of a tax system extends far beyond the raw volume of capital collected. The true measure of legitimacy lies in how those public funds flow back into the community—how transparently they are deployed to reinforce local infrastructure, expand welfare networks, and elevate the living environment. A tax gains its ultimate justification not at the moment of collection, but at the moment of expenditure. As a municipal government demands timely compliance from its citizens, it bears an equal, reciprocal obligation to articulate precisely where and how those resources are being spent.
Pocheon’s current demographic and livelihood stabilization initiatives must ultimately answer this exact call. When property tax revenues transcend dry statistical indicators on a fiscal ledger and translate into palpable improvements in daily civic life, the systemic trust in local governance will naturally solidify. Before they are ever categorized as "taxpayers" or sources of revenue, citizens are the co-inhabitants who give a city its life. Tax administration must therefore be practiced not as a technical science of extraction, but as a discipline of public trust.
The recent advisory by Bae Sang-geun, director of the city's tax division, urging early payments to bypass deadline congestion, reflects this practical philosophy. Given that missing the deadline triggers statutory penalties, the proactive role of government is to insulate citizens from unnecessary financial liabilities through timely communication and frictionless systems. Exceptional governance is not defined by rigid enforcement, but by a preemptive courtesy that prevents the citizen from committing an administrative error.
The property tax rollout is a cyclical annual certainty. Yet, it is within this very repetition that the fundamental character of a local government is laid bare. Assessing accurately, explaining thoroughly, facilitating seamlessly, and returning public wealth transparently to the citizenry—this is the true standard Pocheon must demonstrate. Taxes are inevitably calculated in cold numbers, but the faith of the taxpayer can never be secured by digits alone.
BEST 뉴스
-
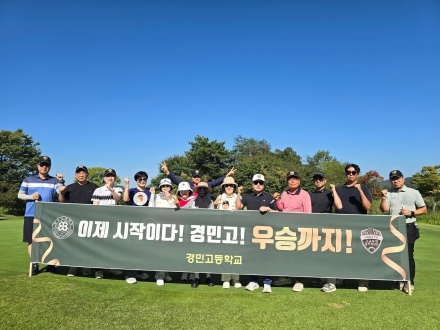
경민고 총동문회 골프팀 SBS골프 고교골프최강전 4강 진출 쾌거 10월 13일 준결승 격돌
경민고 총동문회 골프팀 SBS골프 고교골프최강전 4강 진출 쾌거 10월 13일 준결승 격돌 경민고등학교 총동문회 골프팀이 SBS골프 고교골프최강전 8강전에서 승리를 거두며 당당히 4강 진출의 쾌거를 달성했다. 전국 각지의 명문 고교 동문들이 출전해 모교의 명예와 장학금을 걸고 맞붙... -
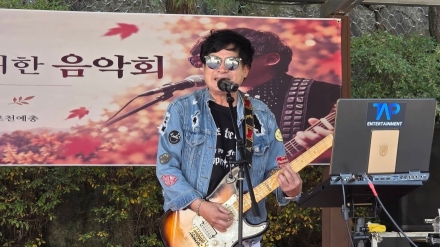
가을 정취 물들이는 허브아일랜드 관광객을 위한 음악회 성황
가을 정취 물들이는 허브아일랜드 관광객을 위한 음악회 성황 가수 김용국 김봉규 단장의 색소폰 연주 가수 화영,황용 등 다채로운 무대 선사 가을 정취를 더하는 허브아일랜드 관광객을 위한 음악회가 열려 방문객들의 큰 호응을 얻고 있다. 트리플에이픽쳐스와 허브아일랜드... -
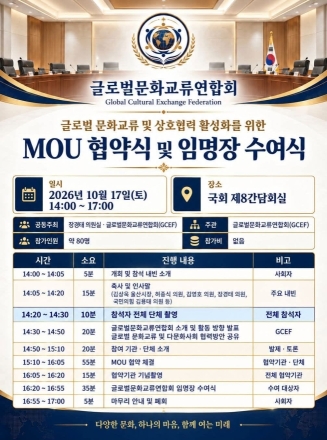
글로벌문화교류연합회 MOU 협약식 및 임명장 수여식 국회서 17일 개최
글로벌문화교류연합회 MOU 협약식 및 임명장 수여식 국회서 17일 개최 글로벌문화교류연합회와 장경태 의원실이 공동으로 주최하는 글로벌 문화교류 및 상호협력 활성화를 위한 MOU 협약식 및 임명장 수여식이 다가오는 10월 17일 토요일 14시부터 17시까지 국회 제8간담회의실에서 성대하게 열린다. 글로벌... -
포천 허브아일랜드 핑크뮬리 축제와 야간개장으로 가을맞이 본격화
포천 허브아일랜드 핑크뮬리 축제와 야간개장으로 가을맞이 본격화 경기 포천시 대표 관광지인 허브아일랜드가 가을 시즌을 맞아 핑크뮬리 축제 개막과 함께 야간개장을 본격적으로 운영하며 방문객 맞이에 나섰다. 허브아일랜드는 지난 9월 19일부터 가을 대표 축제인 핑크뮬리 축제를 시작했다. 스카이 허... -
제16회 계룡군문화축제 10월 1일 화려한 개막
제16회 계룡군문화축제 10월 1일 화려한 개막 대한민국 대표 군문화 축제인 제16회 계룡군문화축제가 오는 10월 1일부터 5일까지 5일간 계룡대 활주로 일대에서 펼쳐진다. 10월 1일 개막식은 오후 6시 30분 미8군 군악대 등의 식전공연을 시작으로 막을 올린다. 이어 오후 7시부터는 소향과 포레스텔라의... -
도쿄 번호판 달고 DMZ까지… 일본 경형 로드스터 고성 통일전망대 주차장 포착
도쿄 번호판 달고 DMZ까지… 일본 경형 로드스터 고성 통일전망대 주차장 포착 29일 오전 강원도 고성군 통일전망대 주차장에 일본 현지 번호판을 부착한 경형 오픈카 한 대가 주차되어 있어 관광객들의 눈길을 사로잡았다. 해당 차량은 일본 다이하츠 사의 2인승 경형 하드탑 컨버터블인 '코펜 세로' 모델로...
전체댓글 0
실시간뉴스

추천뉴스


의정부시
more +단체
more +-

금감원 공시 개편에 삼천당제약 ‘프로핏 쉐어’ 재평가… ‘진가’ 고개를 들다
금융감독원이 제약·바이오 기업의 공시 체계를 전면 개편하고 계약금과 마일스톤, 로열티 및 이익배분 ... -

포천 신북면 ‘포담장터’ 7월 11일 개장… 먹거리·공연·나눔밥상까지 풍성
경기 포천시 신북면에서 지역 주민과 관광객이 함께 즐길 수 있는 먹거리 장터가 열린다. 포천 신북면 ... -

[메트로기획] 붓끝에 되살린 소동파의 철학
소동파(蘇軾)의 대표 산문 〈전적벽부(前赤壁賦)〉가 이종훈 포천문화원장의 필치로 대형 서예 작품으... -

[메트로기획] 모수국과 무지랭이골에 대한 연구 ①
경기 의정부시 고산주민센터에서 진행하는 치매예방 프로그램 ‘웃음빵빵 두뇌짱짱’ 수업 시간이었다. ...
포토뉴스
more +-

90세 노모가 입혀준 붉은 점퍼 소통과 효심으로 그리는 포천의 미래
90세 노모가 입혀준 붉은 점퍼 소통과 효심으로 그리는 포천의 미래 정치인의 선거복은 흔히 당적을 상징하지만 백영현 포천시장 후보에게 붉은 점퍼는 그 이상의 특별한 의미를 지닌다. 최근 90세 노모가 아들에게 직접 선거 운동복을 입혀주는 모습이 포착되면서 지역 사회에 잔잔한 감동을 전하고 ... -

국민의힘, 포천 시의원 선거 ‘위기론’ 확산... 승부수는 ‘필승 전략공천’
국민의힘, 포천 시의원 선거 ‘위기론’ 확산... 승부수는 ‘필승 전략공천’ 가선거구 서과석·나선거구 안애경 전면 배치설... 박윤경 후보 비례대표 선회론도 ‘솔솔’ 오는 6월 3일 제9회 전국동시지방선거를 앞두고 포천 지역 국민의힘 진영 내에서 위기감이 고조되고 있다. 선거 판세가 안개 속으... -

임종훈 포천시의장, '험로' 무소속 시의원 3선 도전...
"포천 향한 진심으로 승부" 임종훈 포천시의회 의장이 다가오는 지방선거에서 포천시장 출마 대신 '무소속으로 시의원 3선 재도전'이라는 파격적인 행보를 결정하며 지역 정가의 이목을 집중시키고 있다.그동안 유력한 시장 후보군으로 거론되며 체급을 키워온 임 의장의 이번 결정은 정치적 영달을 위한 '높... -
가을 정취 물들이는 허브아일랜드 관광객을 위한 음악회 성황
가을 정취 물들이는 허브아일랜드 관광객을 위한 음악회 성황 가수 김용국 김봉규 단장의 색소폰 연주 가수 화영,황용 등 다채로운 무대 선사 가을 정취를 더하는 허브아일랜드 관광객을 위한 음악회가 열려 방문객들의 큰 호응을 얻고 있다. 트리플에이픽쳐스와 허브아일랜드가 주최 주관하고 포천...
